Property Investment Strategies in the UK (2026): How to Choose Between BTL, HMO, BRRR, Flips and Short Lets
No property investment strategy suits everyone. Here is how buy-to-let, HMOs, BRRR, flips, short lets and commercial property compare on capital, time, regulation and tax, and six tests for choosing yours.
Quick answer: The right property investment strategy depends on your capital, your time, your tax position and what you want the money to do. Single-let buy-to-let suits investors who want steady income with low effort. HMOs and short lets produce more income but need far more management and licensing. BRRR suits investors who want to recycle capital and can manage a refurbishment. Flips suit those chasing a lump sum who accept trading tax and market timing risk. Before choosing a property investment strategy, test it against six things: all-in capital, management time, local evidence, regulation, finance appetite and exit options.
Most property investment advice starts with the strategy and works backwards to the investor. "HMOs yield 12%", "BRRR lets you pull all your money out", "Airbnb beats long lets". Each of those can be true for one investor and ruinous for another. A property investment strategy has to fit the person running it: how much cash they have, how much time they can give it, how they are taxed, and whether they need income now or growth later. This guide compares the main UK property investment strategies and gives a simple framework for choosing between them.
The market backdrop matters too. According to the ONS, average UK private rent reached £1,400 a month in the 12 months to August 2026, up 3.8%, while the average UK house price was £273,000, up just 1.4%. That puts the national average gross yield at roughly 6%, with rents rising faster than prices. London is the exception on prices, down 3.3% over the year. And most landlords are small: the government's English Private Landlord Survey 2024 found 45% own a single rental property and just over half manage their lettings without an agent.
How do the main UK property investment strategies compare?
| Strategy | Capital needed | Management time | Main return | Key regulation |
|---|---|---|---|---|
| Single-let buy-to-let | Deposit (usually 25%) plus costs | Low | Income and long-term growth | Renters' Rights Act, EPC rules, deposit protection |
| HMO | Higher: purchase plus fit-out to licensing standards | High | Higher income | HMO licensing, Article 4 planning, room sizes |
| BRRR | Full purchase and refurb until refinance | High during works, then low | Recycled capital and equity | Building regulations, lender six-month rules |
| Flip | Full purchase and refurb until sale | High | One-off profit | Trading income tax, building regulations |
| Short let / serviced accommodation | Purchase plus furnishing | Very high, or paid management | Higher gross income, more volatile | Planning (90-night rule in London), local licensing |
| Rent-to-rent | Low: deposit, furnishing, fees | Very high | Margin between rent paid and received | Landlord consent, HMO licensing, redress |
| Commercial and mixed-use | Higher, with bigger deposits | Low to medium | Income on longer leases | Commercial lease law, non-residential stamp duty |
How do you choose a property investment strategy? Six tests
1. All-in capital, not just the deposit
Add up everything the strategy needs before it produces a return: deposit, stamp duty (including the 5% surcharge on additional dwellings), legal fees, survey, works, furnishing, licensing, finance fees, holding costs and a contingency. A BRRR or flip ties up the full purchase and refurbishment cost until the refinance or sale. A buy-to-let ties up the deposit and costs for years. Our stamp duty calculator and Deal Analyser give you the real capital figure.
2. Management time
A single-let flat with a good tenant might need a few hours a year. An HMO with five tenants, shared bills and licence conditions is a small business. A short let is a hospitality business with guest messages at midnight. Either do it yourself honestly or price in professional management, and see if the numbers still work.
3. Local evidence
Every strategy lives or dies on local demand. Check achieved rents, not asking rents; sold prices, not listings; and competing supply. The ONS private rent and house price bulletin shows regional trends, but the street-level evidence matters more. Our comparison of Liverpool and London for investors shows how differently the same strategy performs in two markets.
4. Regulation
Regulation now shapes every strategy. The Renters' Rights Act ended section 21 evictions from 1 May 2026 and moved most tenancies to periodic terms. The minimum energy efficiency standard is rising to EPC C by 1 October 2030. HMOs need licensing, and short lets face planning limits we cover in our short-let planning guide. The furnished holiday lettings tax regime was abolished from April 2025, removing the tax advantages short lets used to have over long lets.
5. Tax and ownership structure
Individual landlords can't deduct mortgage interest in full under Section 24, and property income tax rates rise to 22%, 42% and 47% from April 2027. Limited companies keep full interest relief but pay corporation tax and further tax on extracting profits. Flipping is usually taxed as trading income rather than capital gains. The best strategy on a pre-tax spreadsheet can be the worst after tax. Compare structures with our limited company vs personal calculator.
6. Finance appetite and exit options
Lenders treat each strategy differently. Single-let buy-to-let has the widest choice of mortgages. HMOs and short lets need specialist lenders. BRRR and flips rely on bridging finance and a clean exit. A strong property investment strategy has more than one exit: if the refinance values low, can you sell? If the sale stalls, can you let it? If you can only exit one way, the strategy is fragile.
Which property investment strategy fits which investor?
Limited time, steady income wanted
Single-let buy-to-let in an area with solid tenant demand, ideally with professional management. Accept lower yields in return for fewer problems. Our guide to what counts as a good rental yield sets realistic expectations, and the rental yield calculator tests any listing.
Capital to recycle, able to manage works
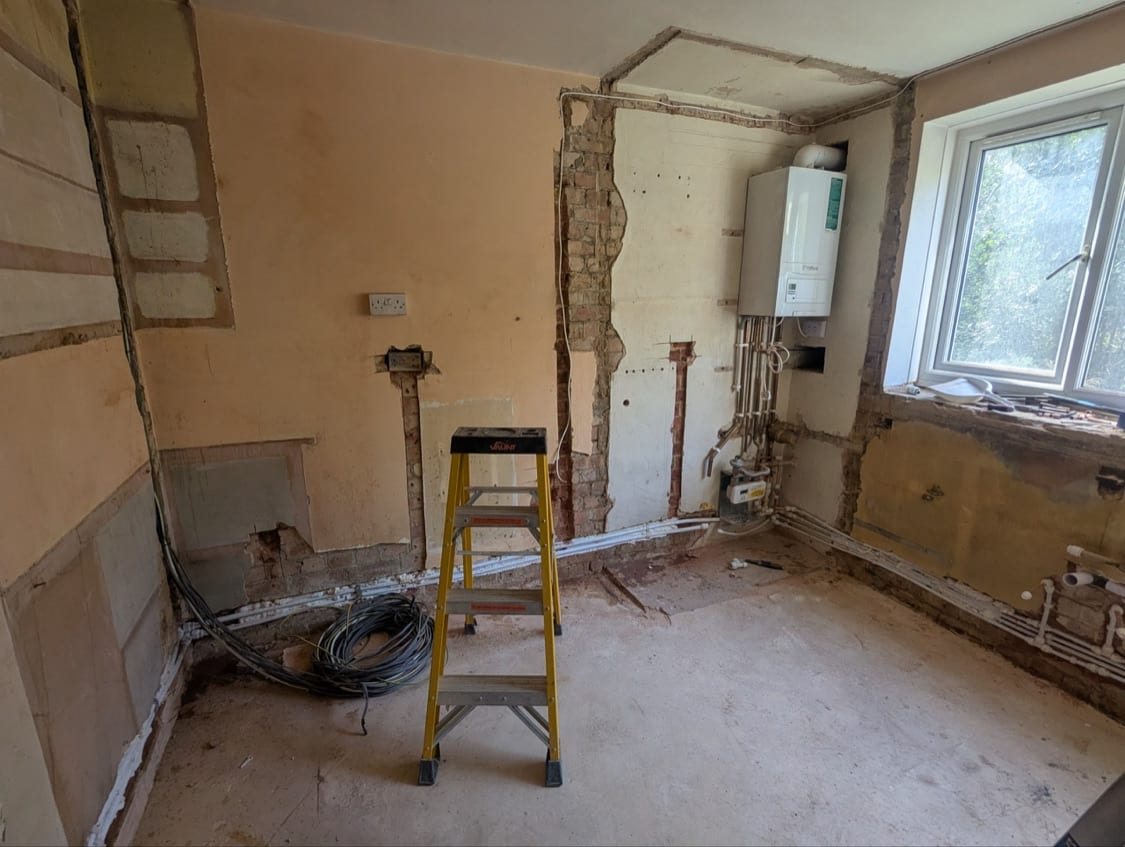
BRRR: buy below value because of condition, refurbish, refinance onto a buy-to-let mortgage and pull out as much capital as the new valuation allows. This is our own core strategy, and our Innes Gardens project shows it in practice, week by week.
Lump sum wanted, comfortable with market risk
Flips. Profit arrives in one go but is exposed to the sale market at the point you finish, and is typically taxed as income. Keep timelines short and margins wide.
Higher income wanted, willing to run a business
HMOs or short lets, with licensing, planning and management costs fully priced in. Our HMO yield calculator and Airbnb calculator include the costs that headline yields leave out.
Larger capital, prefers longer leases
Commercial or mixed-use property, where tenants often sign longer leases and take on repairs. Voids can be longer and lenders ask for bigger deposits. Some commercial buildings also carry a residential upside, which we cover in our guide to commercial-to-residential conversion.
What are the common mistakes when choosing a strategy?
- Choosing on gross yield alone. A 12% gross HMO yield can be a lower net return than a 6% single let once management, bills, voids and licensing are paid.
- Ignoring your own time. Unpaid hours are still a cost. If you'd pay someone else to do it, count it.
- Following last year's rules. Tax, tenancy and energy rules have all changed recently. Check that the strategy still works under the current rules, not the ones in an old course or book.
- Only one exit. Plan the fallback before you buy.
Frequently Asked Questions
What is the best property investment strategy for beginners?
For most beginners, a single-let buy-to-let in an area they know, bought with a sensible deposit and a realistic rent. It has the widest mortgage choice, the simplest management and the fewest licensing requirements. Value-add strategies are easier once you've done one straightforward purchase.
Which property strategy gives the highest return?
On paper, HMOs, short lets and BRRR usually show the highest returns on capital. In practice they also carry the most management, regulatory and execution risk. Compare net returns after all costs, tax and your own time.
How much money do I need to start investing in property?
For a buy-to-let, typically a 25% deposit plus stamp duty, fees and a buffer. For BRRR or flips, you need enough to fund the purchase and works until the refinance or sale, even with bridging finance. Rent-to-rent needs the least capital but the most time and legal care.
Can I combine strategies?
Yes. Many portfolios mix a stable core of single lets with occasional value-add projects. Just make sure each deal is judged on its own numbers, and that one strategy's cash needs don't put another at risk.
Is buy-to-let still worth it in 2026?
It can be, but the margins are thinner than a decade ago. National average gross yields sit around 6%, rents are rising faster than prices, and higher property income tax rates arrive in April 2027. Buy-to-let works best where the rent covers a stressed mortgage comfortably and you are investing for the long term, not for quick cash flow.
Should I buy property through a limited company?
It depends on your tax band, how many properties you plan to hold and whether you need the income personally. Only 6% of landlords operate through a company, according to the English Private Landlord Survey 2024, but the share is rising because companies keep full mortgage interest relief. Model both routes before you buy, because moving a property into a company later triggers stamp duty and capital gains tax.
Should I manage my rental property myself or use an agent?
Just over half of landlords self-manage. That works for a single let near where you live. For HMOs, short lets or a property far away, professional management usually pays for itself in faster lettings, fewer voids and compliance you don't have to track yourself.
Key Takeaways
- No property investment strategy is best for everyone. The right one fits your capital, time, tax position and goals.
- Test any strategy on all-in capital, management time, local evidence, regulation, tax structure, and finance and exit options.
- Recent changes (the Renters' Rights Act, EPC C by 2030, the end of the FHL tax regime and higher property income tax from 2027) affect every strategy.
- Compare net returns after costs, tax and your own time, not gross yields.
- Always have more than one exit before you buy.
This article is general information, not financial or tax advice. The right strategy depends on your personal circumstances. Speak to a qualified financial adviser, mortgage broker and accountant before investing.