What Is the BRRR Strategy? UK Investor Guide (2026)
Buy, Refurbish, Rent, Refinance, Repeat: the strategy that lets you recycle capital into the next deal instead of finding a fresh deposit every time. How it actually works, and where it breaks.
Quick answer: BRRR (Buy, Refurbish, Rent, Refinance, Repeat) means buying a property below market value, adding value through refurbishment, letting it out, then refinancing at the new higher valuation to pull some or all of your original capital back out and reuse it on the next purchase. It works well when you buy at the right price and the refinance valuation holds up; it breaks when either of those assumptions doesn't.
What Does BRRR Stand For?
BRRR is Buy, Refurbish, Rent, Refinance, Repeat. Each stage builds directly on the one before it. Rushing the buy or the refurbishment doesn't just cost you on that step, it caps what the refinance can actually recover later.
Step 1: Buy Below Market Value
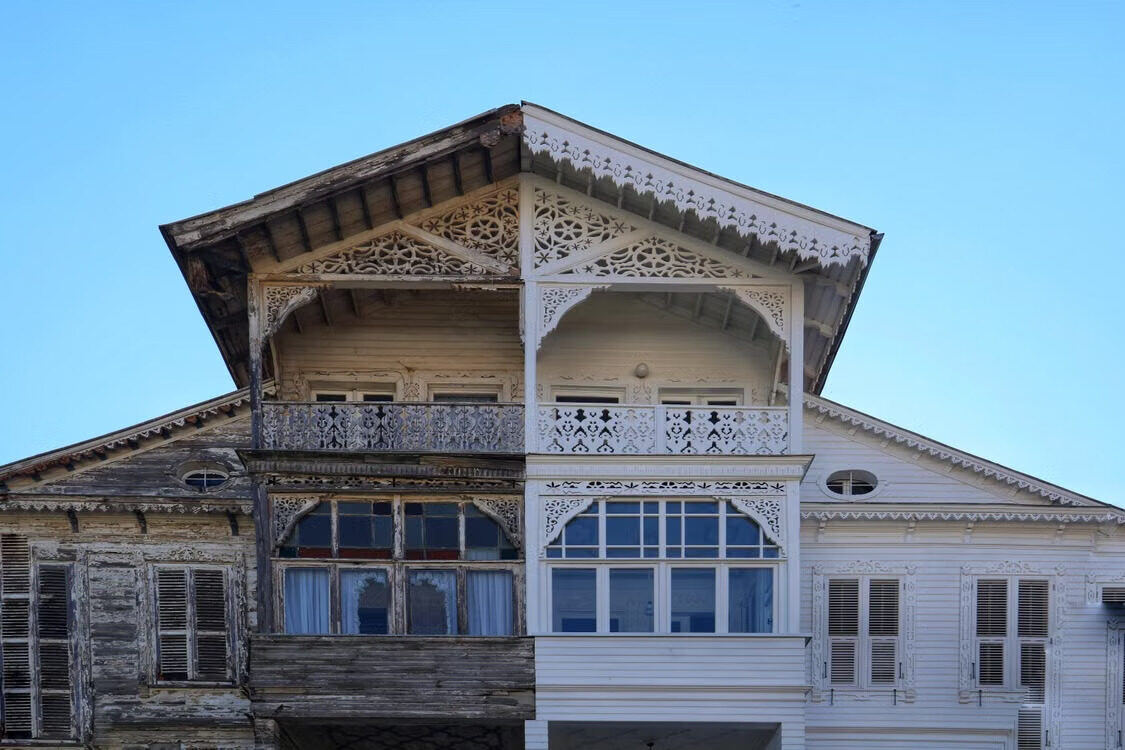
Every successful BRRR project starts with buying well. The goal isn't finding a "cheap" property. It's finding one with genuine potential to increase in value once worked on. Common targets: tired or outdated homes, probate properties, auction purchases, poorly presented rentals, properties needing modernisation, and homes with scope to improve the layout or add bedrooms. Buying below market value builds in a margin of safety and increases how much capital you're likely to recover at refinance.
How Are BRRR Properties Funded?
Many BRRR properties aren't mortgageable in their starting condition, so investors typically fund the purchase with cash, a bridging loan to move fast, or specialist refurbishment finance. Which one fits depends on the property's condition and your exit strategy, not just on rate. On some deals, a purchase option agreement can also secure the right to buy at a fixed price without committing capital upfront.
Step 2: Refurbish to Add Value
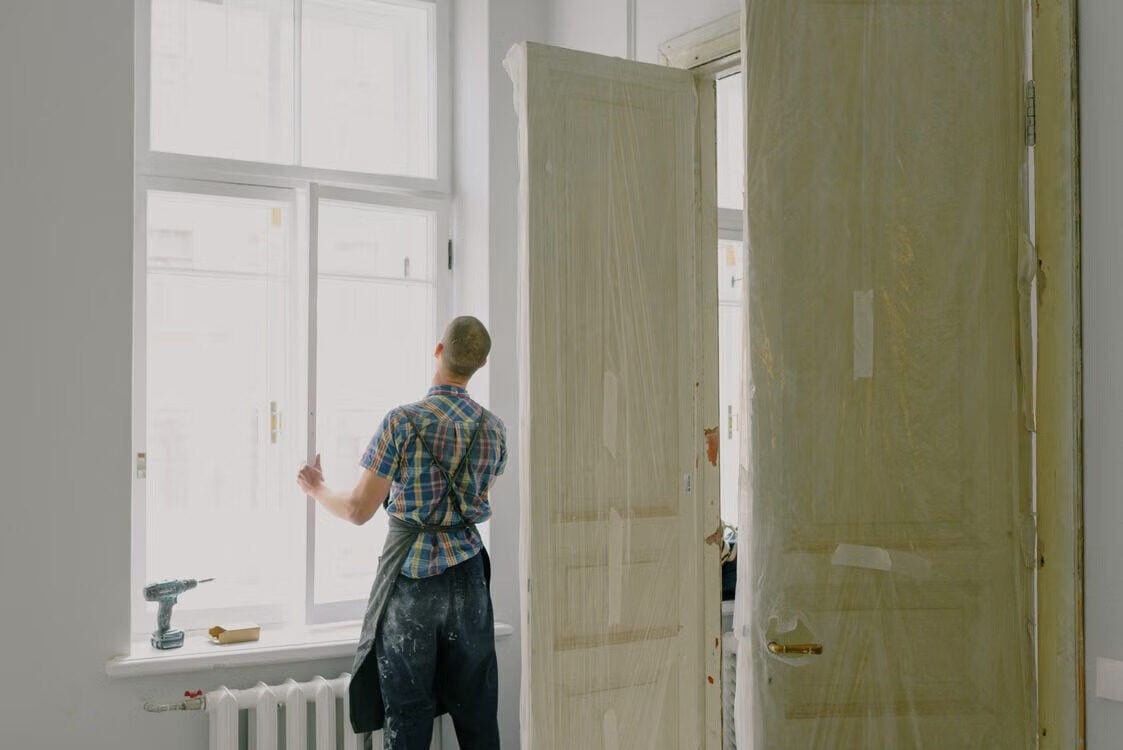
This is where value actually gets created. Rather than just decorating, successful BRRR investors target improvements that lift both market value and rental appeal: new kitchens and bathrooms, rewiring and plumbing upgrades, new heating systems, improved EPC ratings, reconfigured layouts, additional bedrooms, and loft or garage conversions where they genuinely stack up. The objective isn't spending as much as possible. It's spending on the improvements that return the most. Build a detailed budget with a contingency for unexpected costs before you start, not once you're mid-project.
Step 3: Rent the Property
Once refurbished, the property is let to tenants. Strong rental income matters here for a reason beyond cash flow. Lenders assess affordability at the refinancing stage based on that rent. Before advertising, make sure the property meets all legal requirements: a Gas Safety Certificate, an Electrical Installation Condition Report (EICR), EPC compliance, smoke and carbon monoxide alarms, and Right to Rent checks where applicable. A well-presented property in a strong rental market also tends to achieve higher rent and better-quality tenants, which feeds straight back into the refinance.
Step 4: Refinance
Once the property is improved and let, most investors refinance onto a standard long-term buy-to-let mortgage, replacing the short-term finance and releasing part of the capital tied up in the project. Lenders differ a lot on which lenders actually fund BRRR deals, and by how much. How much comes back out depends on the lender's valuation, the property's rental income, loan-to-value limits, affordability criteria, and the individual lender's underwriting policy. Many buy-to-let lenders will go up to 75% LTV, though this varies by lender and by borrower. The more genuine value you've added, the more capital you're likely to recycle, but the valuation is the lender's surveyor's opinion, not yours.
Step 5: Repeat
Capital released at refinance becomes the deposit for the next purchase. Over time, this lets investors grow a portfolio faster than buying traditional buy-to-lets with fresh savings every time: the ability to recycle capital, rather than needing a full new deposit on every deal, is what makes BRRR attractive to investors building at pace.
A Worked BRRR Example
| Stage | Amount |
|---|---|
| Purchase price | £120,000 |
| Refurbishment & buying costs | £30,000 |
| Total investment | £150,000 |
| Post-refurbishment value | £200,000 |
| 75% LTV mortgage | £150,000 |
| Monthly rent | £1,100 |
In this illustration, the refinance covers the original investment in full, leaving the investor holding a £200,000 rental property while having recovered their initial capital. In practice, every project differs: surveyor valuations, lender criteria, and refurbishment cost all move the final outcome, and it's rarely this clean.
Common BRRR Risks
Refurbishment Cost Overruns
Building work routinely costs more than expected. Budget a genuine contingency and get detailed quotations before you buy, not after you've already exchanged.
Down Valuations
One of the biggest risks is the lender's surveyor valuing the property below what you expected. If that happens, more of your own money stays in the deal than planned. Buying at the right price in the first place is the main defence against this. You can't negotiate a valuation after the fact.
Bridging Finance Costs
Bridging finance is a genuinely useful tool but significantly more expensive than a standard mortgage. Delays to refurbishment or refinancing eat into profit fast on a facility charging monthly interest, which is why a clear exit strategy has to exist before you draw the bridge, not once it's already running.
Refinancing Timelines
Many buy-to-let lenders apply a minimum ownership period before they'll refinance against the property's current market value rather than the price you paid, commonly referred to as the "6-month rule." Policies vary between lenders, so confirm the exit lender's actual seasoning requirement with a mortgage broker before you buy, not once the refurb is finished and you need the exit to work.
Why Investors Choose BRRR
Traditional buy-to-let investing needs a fresh deposit on every purchase, and most investors eventually run out of readily available capital that way. BRRR is built to solve that by recycling funds already invested, rather than relying purely on house price growth, you actively create value through refurbishment and use refinancing to fund the next acquisition. For investors with the right skills, planning, and finance in place, that's a genuinely effective way to build a larger portfolio faster than savings alone would allow.
Is BRRR Right for Beginners?
Yes, but it shouldn't be rushed. Many successful investors start with straightforward cosmetic refurbishments before moving to larger renovation projects. A sensible first BRRR project has a realistic refurbishment budget, sits in a strong local rental market, is backed by a reliable team of tradespeople, uses conservative financial assumptions, and has a clear refinancing strategy agreed before purchase. Experience becomes progressively more valuable as the projects get more complex. It's not a strategy where the fifth deal should look like the first.
Calculate Your BRRR Deal Before You Buy
The success of a BRRR investment is largely decided before completion, not after: accurately estimating purchase costs, refurbishment spend, rental income, and refinance value is the actual work. Our Deal Analyser models purchase costs, stamp duty, refurbishment budget, bridging cost, rental yield, cash flow, and the resulting cash-on-cash return and capital left in the deal after refinance. Run the numbers before making an offer, not after you've already committed.
Frequently Asked Questions
Can beginners use the BRRR strategy?
Yes. Many investors start with smaller refurbishment projects before progressing to larger value-add developments. The key is matching project size to your actual experience and financial resources, not the other way round.
Do I need cash to start BRRR?
Usually yes. Even when using bridging finance, you typically still need funds for the deposit, stamp duty, legal fees, any refurbishment cost the finance doesn't cover, interest payments, and a contingency reserve.
Is the 6-month rule a legal requirement?
No. The "6-month rule" investors talk about is generally a lending policy, not a legal one, and it varies between lenders. Get mortgage advice before relying on a specific refinancing timeline for your exit.
Is money released during refinancing taxable?
Borrowing additional money through refinancing isn't normally treated as taxable income, because you're increasing debt rather than receiving income or selling the property. Tax treatment still depends on individual circumstances, so get professional advice rather than assuming.
Key Takeaways
- Profit is made when you buy well, not at the refinance stage.
- Successful refurbishment adds both rental value and market value, not just kerb appeal.
- A refinance is never guaranteed. It depends on lender criteria and the surveyor's valuation.
- Always budget for delays, unexpected costs, and valuation risk before you buy.
- Careful analysis before purchase is the foundation of every BRRR project that actually works.
This guide is for general information only and isn't financial, mortgage, or tax advice. Lending criteria, valuation methods, and property values vary between lenders and individual circumstances.