Liverpool vs London: Where the Numbers Work Better for Property Investors
We operate in both cities. Here's an honest comparison of yields, capital growth, and operational realities in Liverpool versus London.
Quick answer: Neither city is universally "better". They suit different strategies. Liverpool typically delivers higher gross rental yields (roughly 5-7% in solid areas) at a much lower entry price, favouring cash flow and faster capital recycling. London typically delivers lower yields (roughly 3-5%) but has historically shown stronger long-term capital growth, at a materially higher entry cost and higher cash stamp duty bill. The right city depends on whether you're optimising for monthly income or long-term capital growth, and what capital you're starting with.
Why Compare Liverpool and London at All?
We're active in both cities, and the question of which is "better" comes up constantly from investors sizing up where to deploy capital. It's the wrong question, framed that way. Liverpool and London aren't competing for the same investor goal. They solve different problems, and the useful comparison is which problem you actually have.
Yield vs Capital Growth
The clearest structural difference between the two markets is where the return comes from.
| Liverpool | London | |
|---|---|---|
| Typical gross yield | 5-7% in solid rental areas | 3-5% in most zones |
| Historical capital growth | Steadier, more moderate | Historically stronger over the long term, though cyclical |
| Typical three-bed entry price | Roughly £200,000 for a solid property | Roughly £500,000+ for something comparable |
| Tenant demand driver | Regeneration, students, relocating professionals | International demand, constrained supply, transport links |
| Market character | More straightforward, more predictable | More complex, more micro-market dependent |
Liverpool consistently produces stronger cash flow because rents are high relative to purchase price. London's appeal has historically been capital growth, driven by constrained land supply, international capital, and its position as a global city, though that growth has been more cyclical and less guaranteed in recent years than the "London always goes up" assumption suggests. Neither pattern is fixed forever, but it's held reliably enough, for long enough, to shape how we allocate capital between the two.
Entry Cost and What It Actually Means for Risk
The price gap between the two cities changes more than affordability. It changes the risk profile of every deal.
A £200,000 Liverpool purchase and a £500,000+ London purchase carry very different consequences if a refurbishment overruns, a valuation comes in lower than expected, or a void period runs longer than planned. The absolute cash exposure per project is lower in Liverpool, which means more deals can run in parallel from the same capital base, and a single underperforming project does proportionally less damage to the portfolio. That's a genuine advantage for investors building a larger number of smaller positions rather than concentrating capital in fewer, larger ones.
Higher purchase prices in London also mean a materially bigger stamp duty bill in cash terms, even before any additional-property surcharge is applied. See our stamp duty guide for exactly how that scales. On a leveraged deal, a lower entry price also means a smaller deposit in absolute terms, which is often the more binding constraint for investors recycling capital between projects rather than the yield itself.
How Rising Rates Affect Each Market Differently
Mortgage affordability stress-testing (the interest coverage ratio, or ICR, lenders apply) is directly a function of the rent-to-price ratio, which is exactly where the two markets diverge most. A Liverpool property yielding 6% clears an ICR stress test far more comfortably than a London property yielding 3.5% at the same purchase price relative to rent, because there's simply more rental income relative to the mortgage to work with. In a higher-rate environment, this isn't a marginal detail. It's often the difference between a deal that's mortgageable at a sensible loan-to-value and one that isn't, independent of the property's underlying quality. Investors evaluating London opportunities in particular should stress-test financing at a rate meaningfully above today's, not just today's actual rate.
Market Dynamics: What Actually Drives Demand
Liverpool
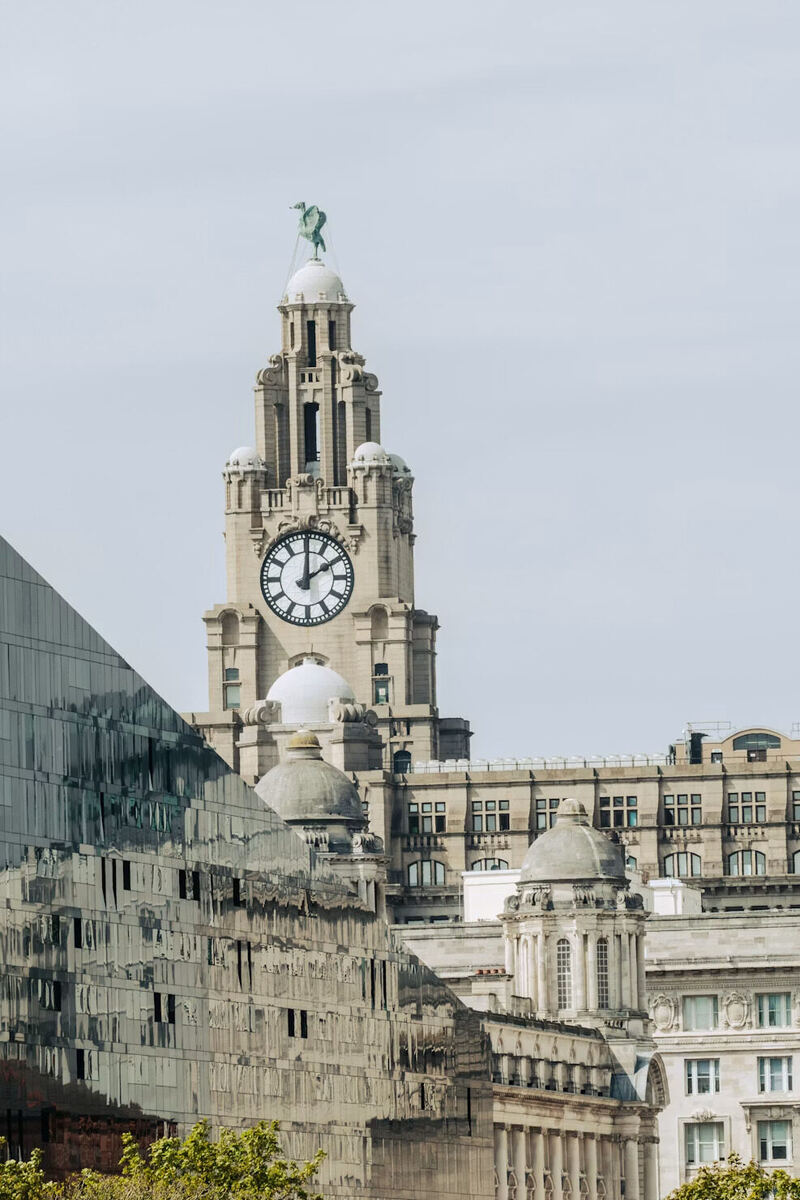
Two large, growing universities anchor Liverpool's rental demand, alongside an ongoing regeneration programme across several districts and a cost of living well below London's. Professionals relocating from pricier cities notice that gap quickly. Underwriting here is genuinely simpler: fewer micro-market swings, steadier values, more predictable running costs. It's not uniform opportunity, though. Regeneration areas still need real diligence on funding and pace rather than the promise of it, and a few new-build pockets have seen enough oversupply to soften rents and slow growth relative to established streets.
London
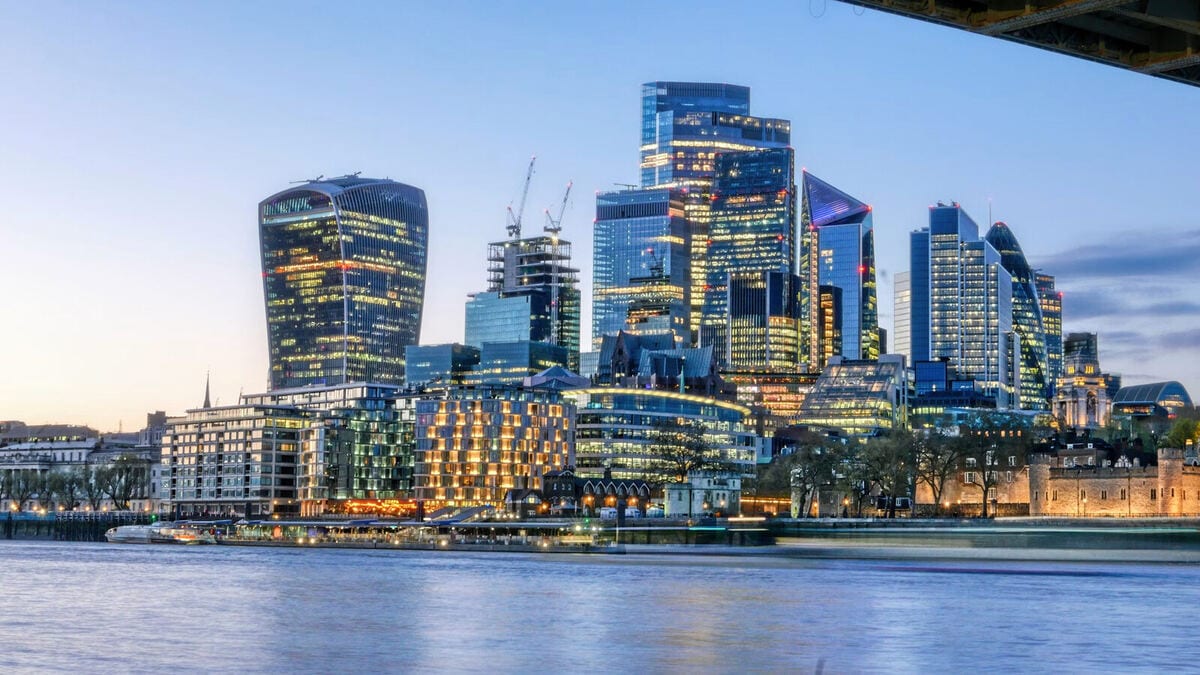
London's demand comes from its position as a global city: international tenants, corporate lets, housing supply that can't keep pace with a very large population, and transport links few other UK cities can match. That demand is real. Reading the market is the hard part. Performance swings enormously between adjacent postcodes, let alone boroughs, so a single "London yield" headline can hide very different outcomes depending on the specific micro-market. Granular local knowledge matters far more here than city-level averages ever will.
Risks Specific to Each City
- Liverpool: selective oversupply in some new-build developments; regeneration timelines that run slower than marketed; and a ceiling on achievable rents in some areas that limits how much a refurbishment can actually move the numbers.
- London: a much higher absolute cash exposure per deal; yields that can leave thin margin once financing costs and voids are accounted for, especially at higher interest rates; and a capital growth story that has been genuinely cyclical rather than guaranteed in recent cycles.
How We Actually Allocate Between the Two
We use Liverpool for cash flow and Cheshire-style rental fundamentals, and London for strategic, higher-conviction capital plays where we have strong local knowledge of the specific micro-market. That's not a universal formula. It reflects our own capital position and risk appetite. An investor prioritising monthly income over portfolio size might lean far more heavily toward Liverpool and similar regional cities; an investor with substantial capital and a long time horizon might reasonably weight more toward London, provided the deal is underwritten on realistic yield and financing assumptions rather than historical appreciation continuing indefinitely.
Frequently Asked Questions
Is Liverpool a good city for buy-to-let investment?
For cash flow-focused strategies, generally yes: strong tenant demand from students and professionals, low entry prices relative to rent, and an active regeneration programme support solid gross yields in well-selected areas. As with any city, area selection within Liverpool matters more than the city-level average.
Does London still offer good capital growth for investors?
Historically, yes, over long time horizons, but growth has been more cyclical and location-specific in recent years than the older "London always rises" assumption suggests. Treat any specific growth projection with real scepticism and underwrite the deal on today's yield and financing cost, not a hoped-for future price.
Which city has lower stamp duty?
The percentage rates are identical nationally: what differs is the cash amount, because London's higher purchase prices push more of the transaction into higher SDLT bands. In practical terms, buying in London means a materially larger stamp duty bill on a comparable property, not a different rate structure.
Should a first-time investor choose Liverpool or London?
For most first-time investors with limited capital, a lower entry price and stronger cash flow make regional cities like Liverpool an easier place to learn the mechanics of being a landlord without a single mistake being financially catastrophic. That's a starting-point observation, not a rule. The right answer still depends on your specific capital, goals, and risk tolerance.
Key Takeaways
- Liverpool favours cash flow: higher yields, lower entry cost, more straightforward underwriting.
- London favours capital growth historically, at a materially higher entry cost and lower yield.
- Higher interest rates squeeze low-yield London deals harder than higher-yield regional ones on an ICR stress test.
- Stamp duty percentage rates are the same nationally. London's higher prices just mean a bigger cash bill.
- The right city depends on your capital, your goals, and your tolerance for concentration risk, not on which one is "better."
This article reflects our own experience investing in both markets and is for general information only, not investment advice. Property market conditions change, and area-level performance within both cities varies significantly. Do your own local research before committing capital.
Run the Numbers on Either Market
Whichever city you're weighing up, the same discipline applies: model realistic yield, financing cost, and stress-tested affordability before you commit. Our Rental Yield Calculator works out gross yield, net yield, cash-on-cash return, and an ICR stress test for any purchase price and rent, and our BTL Affordability Calculator checks whether a specific deal clears lender criteria at today's rates and a stressed higher rate. Tax treatment doesn't change city to city, but it changes the real return either way. Our UK landlord tax guide covers income tax, Section 24, CGT, and the Ltd company question for whichever market you land in.