Refurb Finished Five Weeks Early, Seven Valuations and Three Exits: Innes Gardens Update
Our Putney flat is finished and furnished. Seven estate agents valued it at £350,000 to £425,000, the new EPC is a C, and we've applied to remortgage at 75% loan-to-value on £450,000. Here's how the numbers line up and why the flat is on the market three ways at once.

Quick answer: The refurbishment of our Innes Gardens flat in Putney finished in the week of 26 October, about five weeks ahead of the early-December target, and the flat was furnished a week later. Seven estate agents valued it between £350,000 and £425,000 for sale and £2,200 to £2,900 a month to rent. The new EPC is a C (77), up from a D (66). We have applied to remortgage at 75% loan-to-value on a value of £450,000, above every agent's figure, with the lender's valuation booked for 9 November, and the flat is now on the market three ways at once: an off-market sale at £425,000, a long let at £2,600 a month and a furnished mid-let.
Our last update on this Putney flat ended with the kitchen half-fitted, the second bathroom dropped and a target of practical completion in early December. Four weeks later the building work is done, the flat is furnished, and the questions have moved from "what goes where" to "what is it worth and how do we get our money back out".
The refurb finished five weeks early
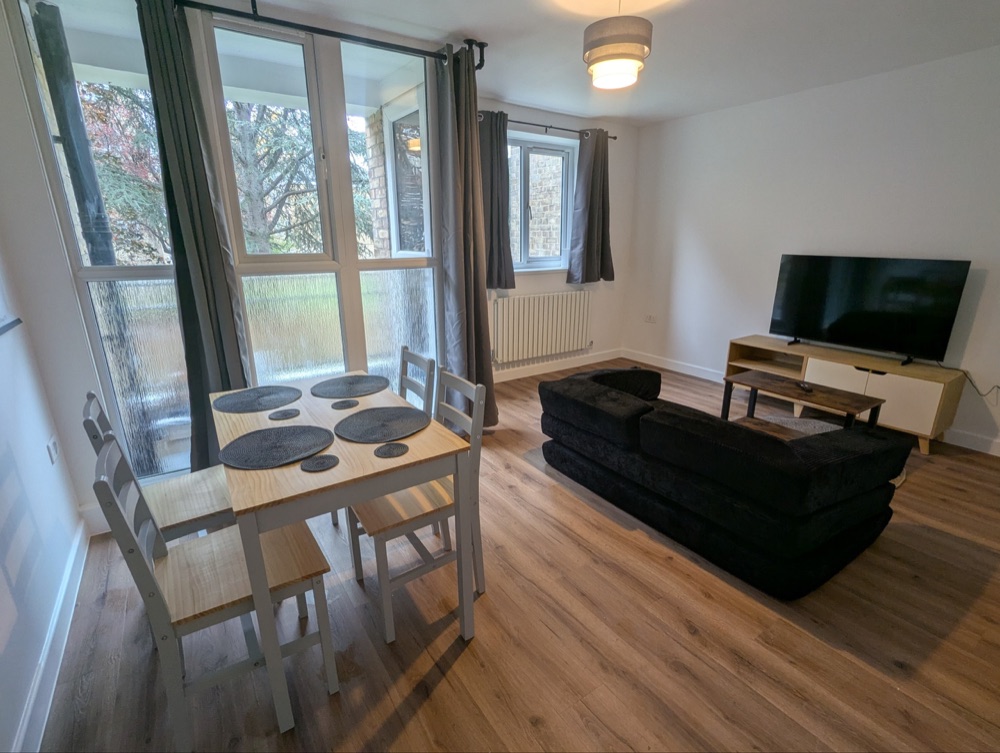
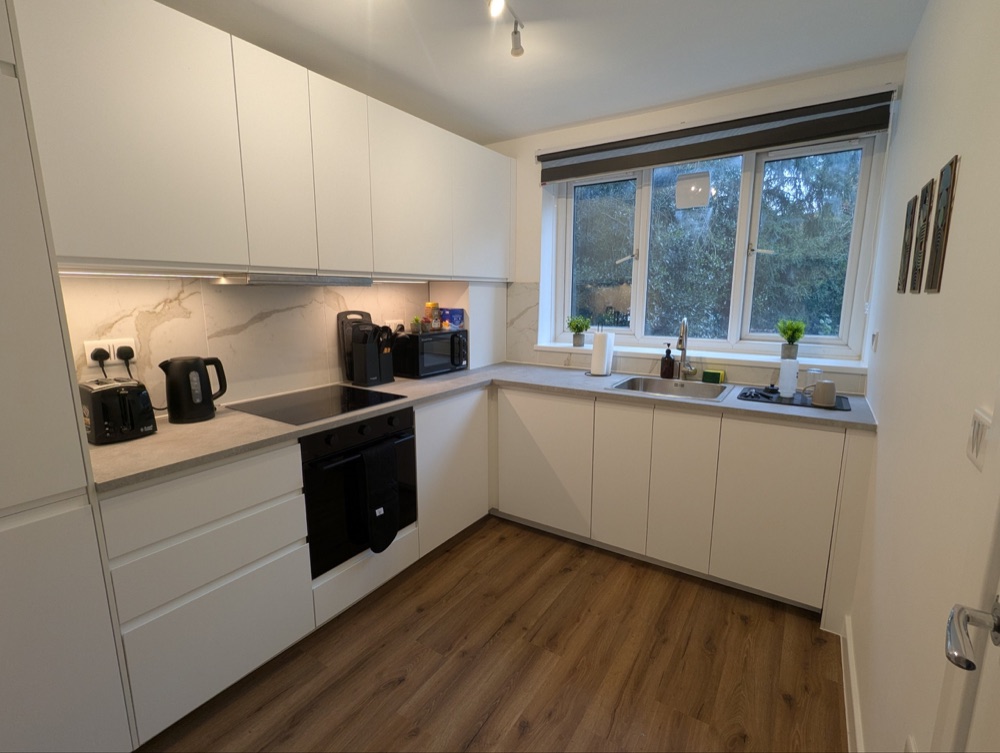
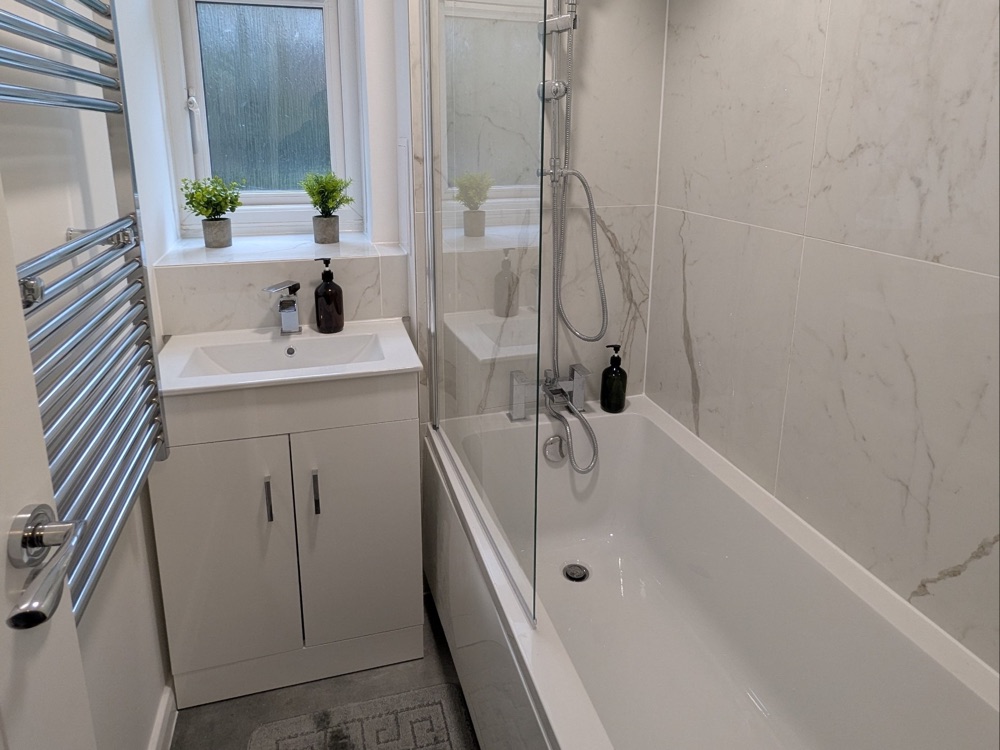
The remaining work from the last update all went in during October: wall tiling in the bathroom and kitchen, the bath, the new WC and both basins, the kitchen appliances, the rest of the SPC flooring, second-fix electrics and decorating. The crew finished in the week of 26 October. We had planned around early December, so the flat is ready roughly five weeks sooner than the schedule we published.
Two certificates are still outstanding: the electrical installation certificate for the rewire, and a reissued gas safety certificate (the first one was issued with the wrong address). Neither stops the flat being shown or valued, but both are needed before a tenant moves in, and a lender's valuer can ask for them.
The early finish matters for the money. The flat is held on a 12-month bridging loan that matures in August 2027, and every month on the bridge costs interest with no rent coming in. Finishing early brings the refinance forward and takes pressure off the maturity date.
Seven estate agent valuations in one day
We booked eight local agents for valuations on 27 October, back to back from 10:30 to 17:00. One gave no exact figure, so seven numbers count. Most agents gave both a sale figure and a rent figure. We have left the agents' names out, because the point is the spread, not who said what.
| Agent | Sale figure | Long-let rent (per month) | Written or verbal |
|---|---|---|---|
| A | £350,000-£370,000 | £2,500-£2,750 | Verbal |
| B | £400,000 | £2,200-£2,300 | Verbal |
| C | £375,000-£400,000 | £2,300-£2,400 | Verbal |
| D | £395,000-£400,000 | £2,700-£2,900 | Rent written, sale verbal |
| E | £400,000-£425,000, recommended asking price £425,000 | Not given | Asking price written |
| F | Recommended asking price £425,000 | £600 a week (about £2,600) | Written |
| G | £375,000-£400,000, recommended marketing price £400,000 | £2,500-£2,750 | Written |
Three things stand out. First, the sale figures cluster around £400,000, with a low outlier at £350,000-£370,000 and two agents at £425,000. That sits inside the £400,000 to £425,000 end value we moved to after dropping the second bathroom, and below the £450,000 the deal was first modelled on. Second, the written letters are careful to say an agent's figure is a marketing or asking price, not a valuation for mortgage purposes. Only the lender's own valuer can set the number the refinance is based on. Third, rent opinions were tighter than sale opinions, mostly £2,300 to £2,900 a month, and one agent also priced a furnished short let at £3,250 to £3,600 a month including bills.
The agents' fees varied as much as their figures. For a sale, quotes ran from 1.5% plus VAT to 2.5% plus VAT, with one fixed fee of £8,500 plus VAT. At £425,000 that is a gap of more than £4,000 between the cheapest and the dearest. For lettings, management fees were 13% to 17% plus VAT of the rent, and some let-only fees were charged monthly for as long as the tenant stays, not once. Since we self-manage, those letting fees are a comparison, not a cost.
EPC C (77), and a floor area that kept changing
The old EPC was a D (66) from 2020, before the refurb and before the boiler was replaced. A new assessment on 2 November, at a cost of £61, came back as a C (77) with a potential B (81). It was lodged on 4 November and is on the government's EPC register. A C matters for two reasons. It is comfortably above the E minimum a landlord needs to let today under the minimum energy efficiency standard, and it already meets the C rating proposed for rented homes by 2030 (see our MEES guide). The same day, the landlord-supplied appliances were PAT tested for £64, which the selective licence asks for.
The EPC also gave us the floor area: 75 m². The selling agent's first draft brochure said 67 m² and labelled the third bedroom a dining room. We sent back two photos of the room and the EPC figure, and the floorplan was redrawn: the room is now a bedroom of 2.56 x 2.40m and the total is 73 m². A 6 m² difference in stated floor area is not a detail when buyers compare price per square foot, so it is worth checking every floorplan against the EPC before it goes out.
Furnishing a three-bed for under £3,000
We furnished the flat so it can be let furnished or unfurnished and work as a mid-let. Two double divan beds with mattresses, two wardrobes, bedside tables, a sofa bed, a dining set, a TV and cabinet, a standing desk and chair for the third bedroom, kitchen kit, curtains, poles, a kitchen blind and wall art came to just under £3,000, most of it ordered online over a few days. Window coverings alone were about £305.
The one step that saved the most time was measuring every window before ordering anything. We logged each opening, the radiators under the sills and the 240cm ceiling height, and bought curtains and poles to fit that list.
The remortgage: 75% loan-to-value, valuation on 9 November
This is a BRRR project, so the plan has always been to refinance the bridge onto a buy-to-let mortgage once the work is done. Through our broker we have applied for a 5-year fixed, interest-only buy-to-let mortgage at 75% loan-to-value with a specialist lender, on a value of £450,000. That is above every agent's figure, and it is deliberate: agents price for a sale, while the lender's surveyor values the finished flat with its new EPC, floor area and refurbishment evidence. The surveyor is booked for 9 November. If the valuation comes in lower, the loan is simply sized to the lower figure, so aiming at £450,000 has no downside. We passed on another lender, which had a rule of no remortgage within 6 months of purchase and would have pushed the refinance to late February.
The bridge needs about £212,000 to clear. At 75% loan-to-value, a lender valuation of £450,000 releases £337,500 before fees, £425,000 releases £318,750 and £400,000 releases £300,000, so the deal clears its floor even at the bottom of the agents' range. The gap between £450,000 and £400,000 is £37,500 of our own money that either comes back out or stays in the deal. You can model the same trade-off on our Deal Analyser.
One detail in the offer deserves a second look. The early repayment charges run for the full five years, from 5% down to 3%. If we sold the flat in the first two years, the charge would be 5% of the loan, about £17,000, plus the lost product fee. That is why we are not running the sale and the refinance as two separate plans without checking how they interact.
Three ways out, all live at once
Rather than commit to one exit before the valuation, we put the flat in front of three markets in the same week and let the response decide.
- Off-market sale at £425,000. The agent with the highest written figure and the lowest fee (1.5% plus VAT) is offering it quietly to its own registered buyers first, before any portal listing. This is a test of demand, not a decision to sell.
- Long let at £2,600 a month. Listed on 5 November, bills excluded, furnished or unfurnished at the tenant's choice, with a £3,000 deposit (five weeks' rent, the legal cap under the Tenant Fees Act 2019). Since 1 May 2026 every new private let is an assured periodic tenancy with no fixed term.
- Furnished mid-let of two weeks or more. Listed on two booking platforms with a 14-night minimum and a monthly discount, priced so that a month nets about £3,500 after platform commission of 15% to 15.5%. That figure includes council tax, energy, broadband and cleaning every two weeks, so the gap to the £2,600 long let is smaller than it looks.
The mid-let has a hard ceiling in London. Whole-home lets of under 90 consecutive nights are limited to 90 nights a year without planning permission, counted across every platform together. So the mid-let is a bridge to a long let or a sale, not a year-round strategy. Our Airbnb calculator runs the same comparison against a long let, and our guide to short-term let registration covers what changes for hosts in 2027.
What's next
The lender's valuation on 9 November is the number everything else hangs on. If it lands at or near £450,000, refinancing and letting is the likely route. If it lands nearer £400,000, the sale test and the offers it brings carry more weight. Alongside that, we need the electrical certificate and the corrected gas safety certificate in hand before any tenant moves in, and a lease extension is planned once the remortgage completes. We will post the next update when the valuation is back.
Frequently Asked Questions
How many estate agents should you invite to value a flat?
Three is the usual advice, but on a refurbished flat with thin comparable evidence more opinions help. Seven gave us a clear cluster around £400,000 and showed which figures were outliers. Ask each agent to put the figure in writing, and remember that an agent's figure is a marketing price, not a mortgage valuation.
Can you market a flat for sale and to let at the same time?
Yes, and it is a common way to test demand after a refurbishment. Check your mortgage terms first: early repayment charges can make a sale in the first years expensive, and a lender may ask about a sale listing during a refinance. Once a tenant or guest is booked, block the dates on every other channel.
Does an agent's valuation count for a remortgage?
No. A lender relies on its own surveyor's valuation. Agent figures and comparable sales are still useful evidence to give the surveyor, along with the EPC, the floor area and a list of the refurbishment work.
Key Takeaways
- The refurb finished in the week of 26 October, about five weeks ahead of the early-December target, and the flat was furnished for just under £3,000.
- Seven agents valued the flat at £350,000 to £425,000 for sale, clustered around £400,000, and £2,200 to £2,900 a month to let.
- The new EPC is C (77), up from D (66), and it corrected the floor area in the sale brochure from 67 m² to 73 m².
- The remortgage application is at 75% loan-to-value on a £450,000 value, above every agent's figure, with the lender's valuation on 9 November. The bridge clears at any figure the agents gave.
- The flat is live as an off-market sale, a long let and a furnished mid-let at once, and the valuation will decide which exit wins.
This post describes a live, ongoing property project and reflects figures and events as of the dates stated. Agent figures are opinions of marketing price, not valuations. It isn't financial, legal, tax or mortgage advice, and every property and lender will differ.